Better credit decisions. More opportunities for SMEs.

Cygnet Creations helps small businesses become more visible to lenders. We analyse authorised bank statements, digital payments, invoices and cash flow to build a clearer picture of an SME's financial performance and potential repayment capacity.

Built on the records businesses already have

Viable businesses struggle to access financing and growth opportunities.

Small and medium-sized enterprises drive growth, employment and local commerce. Yet many cannot get the financing they need to buy inventory, pay suppliers, acquire equipment, hire staff or expand. The challenge is greatest for women-led, informal and underserved businesses.

For SMEs

Limited access to affordable financing

Too little collateral, no formal credit history, no audited statements.

Incomplete financial records

Payments arrive through transfers, POS terminals, mobile wallets and cash.

Assessments that overlook viable businesses

Conventional checks may miss real revenue, cash flow and repayment capacity.

Costly, complex applications

Repeated documents and visits, long waits, and no idea what to improve.

Hard-to-find financial products

Unclear which loan, repayment structure or facility fits.

Limited access to markets

Little digital presence, and difficulty finding customers, suppliers and partners.

For lenders

Incomplete or inconsistent financial information.

High manual effort to review applications.

Little visibility into businesses with thin credit histories.

Difficulty estimating cash flow and repayment capacity.

Assessment costs out of proportion to small loan amounts.

Risk of inaccurate, biased or incomplete decisions.

Cygnet Creations turns fragmented SME business data into actionable financial intelligence, for SMEs and the lenders who serve them.

Lenders get a more complete view than a traditional credit score alone. SMEs get a clearer understanding of their financial position and a path to suitable financing and growth opportunities.

From business records to a financing decision.

  1. Stage 1

    Profile and consent

    Business profiling

    The business shares its sector, operating history, revenue sources, location, financing needs and intended use of funds.

    Secure data collection

    With consent, the SME provides bank statements, digital payment records, invoices, cash flow information and available credit history.

  2. Stage 2

    Analysis

    AI-powered financial analysis

    Revenue and cash flow patterns, seasonality, recurring costs, outstanding obligations, inconsistencies and gaps in the information.

    Financial profile and credit intelligence

    A structured profile and financing-readiness assessment, with a credit-risk estimate and explanation where the evidence supports it.

  3. Stage 3

    Matching and decision

    Financing opportunity matching

    The profile is matched against participating lenders' eligibility criteria, so businesses stop applying blindly.

    Lender review and decision

    Authorised lenders review the assessment against their own credit policies. The lender keeps responsibility for approval, terms, pricing and disbursement.

  4. Stage 4

    Growth

    Business growth support

    Over time, SMEs use their profiles to showcase products and find customers and suppliers.

    Ongoing financial insights

    With authorised data, businesses track cash flow and see what may improve future financing readiness.

Four parts, one pathway.

AI SME Credit Intelligence

For lenders

Automated statement analysis, revenue and cash flow assessment, anomaly detection, repayment-capacity estimates and explainable summaries for lender review.

Value: more comprehensive and efficient SME assessments, particularly for businesses with limited traditional credit information.

SME Financial Health

For business owners

Income and expenditure summaries, cash flow trends, financing-readiness insights, and checks on which records are complete or missing.

Value: a clearer picture of the business and practical steps to become more finance-ready.

Financing Discovery and Matching

For both

Eligibility checks, product discovery and comparison, required-document lists, and routing to participating lenders.

Value: businesses find potentially suitable options. Lenders receive more organised applications.

Later phase

SME Digital Marketplace

Business storefronts, product and service listings, and connections to customers, suppliers, distributors and support services. Introduced after the core financing workflow is validated.
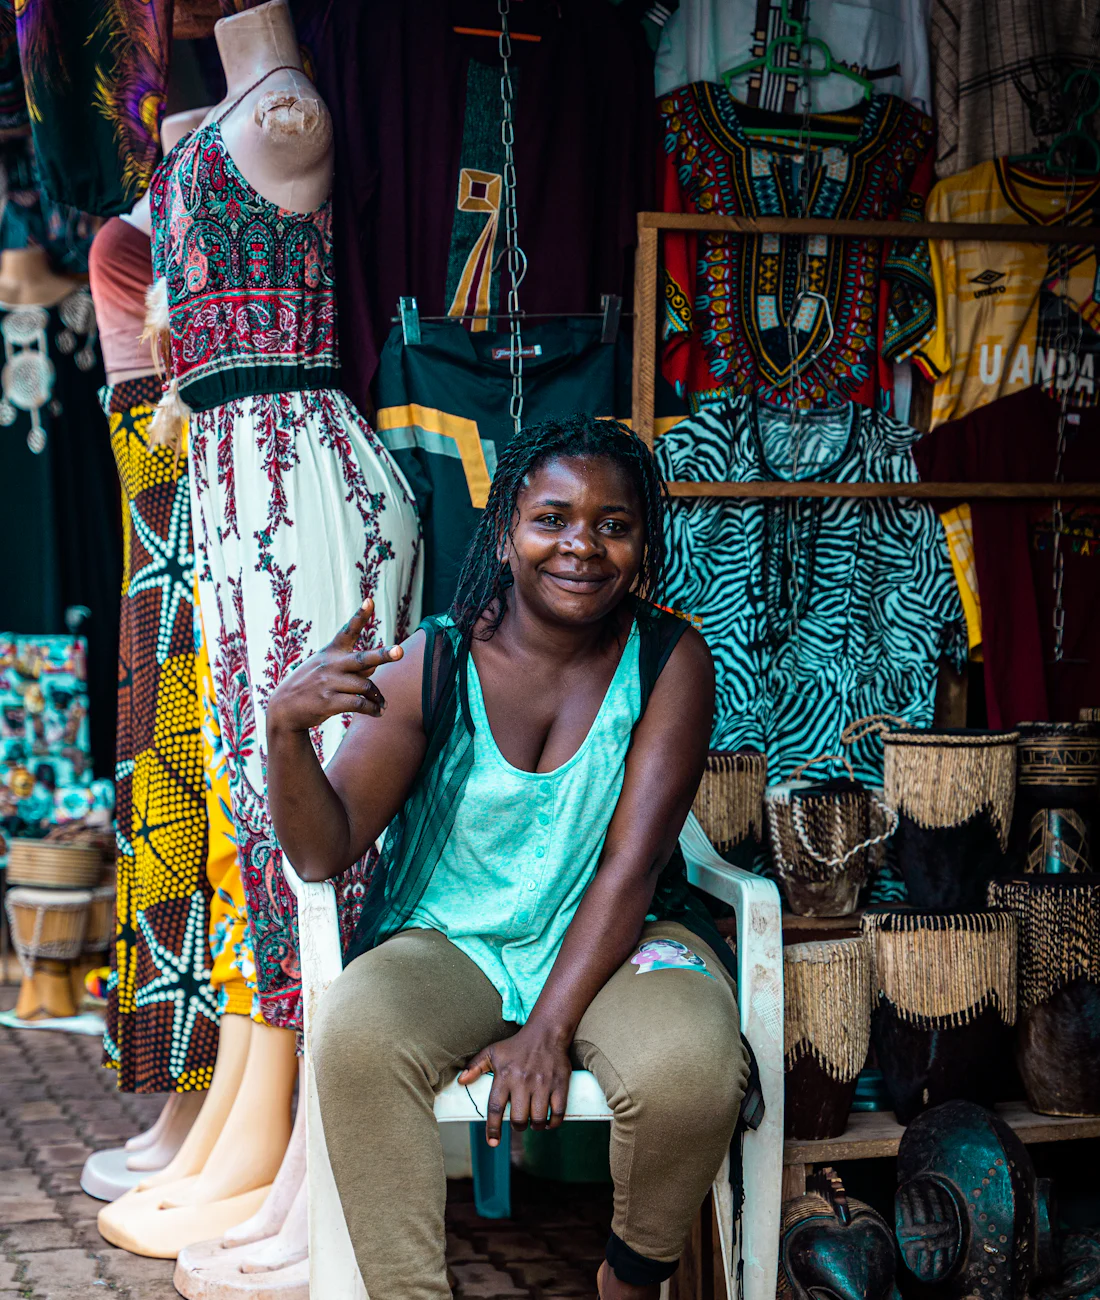
Clearer evidence for lenders. Clearer options for businesses.

For SMEs

Better financial visibility

Organised information on revenue, expenses and cash flow.

Visibility into financing options

Discover suitable products and understand what each application needs.

Greater financing readiness

Find missing records before you apply.

Reduced application friction

Fewer repeated requests where lenders accept the platform's outputs.

Potentially broader access to credit

Better evidence may help viable businesses with limited credit histories receive consideration.

For lenders

More efficient assessment

Less repetitive data extraction and preliminary review.

Better-informed decisions

Structured indicators and evidence alongside your existing credit policies.

Improved SME visibility

Alternative financial information on businesses conventional methods find hard to assess.

Earlier identification of inconsistencies

Information that needs verification is flagged.

Potentially lower assessment costs

Automation makes smaller applications more practical to review.

Improved portfolio monitoring

With appropriate data access, track agreed indicators over time.

For women-led and underserved businesses

Businesses with limited access to conventional credit assessment may benefit from a more comprehensive evaluation of their financial data. This does not guarantee approval. It gives lenders better evidence to assess a wider range of businesses fairly.

Built with lenders, for the businesses they serve.

Financial institutions

Commercial banks, microfinance banks, fintech lenders, development finance institutions and SME-focused financial service providers.

People who use it

SME owners and managers, credit analysts and loan officers, risk and portfolio managers, and SME relationship managers.

Initial focus
  • Retailers and wholesalers
  • Distributors and traders
  • Service businesses
  • Small manufacturers and processors
  • Women-led businesses
  • Digitally active businesses with limited credit history
A clothing and craft retailer seated outside her stall, surrounded by printed fabrics and hand-made drums.

A retailer wants to stock up before the busy season.

The business has traded for several years, receives regular customer payments and has recurring suppliers. The owner has limited formal credit history and lacks some of the financial statements a traditional lender requires.

Without Cygnet Creations

  1. The owner approaches a lender.
  2. The lender requests financial records and supporting documents.
  3. The business struggles to assemble complete information.
  4. The lender reviews the available records by hand.
  5. The application may be delayed, declined or sent back for more information.

With Cygnet Creations

  1. The owner creates a business profile.
  2. The owner provides or authorises access to available records.
  3. The platform organises transaction, invoice and cash flow information.
  4. AI identifies revenue patterns, recurring expenses, inconsistencies and repayment-capacity indicators.
  5. An assessment summary highlights the evidence and what still needs verification.
  6. The owner discovers financing options that may fit.
  7. A lender reviews the information and makes the final decision.

Cygnet Creations helps make the business's financial activity easier to assess. It does not guarantee that the business will receive a loan.

More than a credit score. More than a loan marketplace.

Beyond traditional credit scores

Supplements credit information with authorised transaction, cash flow and invoice data.

Beyond a credit-scoring tool

Connects assessment with financing discovery and, over time, a marketplace.

Beyond a loan marketplace

Helps businesses understand their position, not only browse products.

Designed for incomplete records

Evaluates the evidence a business has and clearly marks what's missing.

A feedback loop for growth

Organised records today can support future assessments, when the business authorises it.

AI that supports lenders' judgement and never replaces it.

Cygnet Creations supports lender underwriting policies. AI outputs are not unquestionable decisions, and missing data is never treated as evidence that a business is uncreditworthy.

  • Explicit consent and data-access controls
  • Explainable assessment factors and human review
  • Fairness testing across SME segments
  • Encryption in transit and at rest
  • Role-based access and audit trails
  • Data minimisation and clear retention policies
  • A process for correcting inaccurate business information

Access to finance based on what a business can show.

We start with AI-powered credit intelligence. Next comes financing discovery and lender connections. Over time, Cygnet Creations grows into an SME marketplace where businesses find customers, suppliers, financing and business services.

  1. NowCredit intelligence
  2. NextFinancing discovery
  3. LaterGrowth marketplace

Questions

Does Cygnet Creations approve loans?

No. Lenders keep responsibility for approval, loan terms, pricing and disbursement.

Does using Cygnet Creations guarantee a loan?

No. It helps make a business's financial activity easier to assess.

What information does it use?

Information the SME provides or authorises: bank statements, digital payment records, invoices, cash flow and available credit history.

What if some records are missing?

The platform identifies the gap and what would fill it. Missing data is not treated as evidence that a business is uncreditworthy.

Do lenders need live integrations to start?

No. Secure document upload works first. Integrations follow as access and partnerships allow.

How is my data protected?

Explicit consent, encryption, role-based access, audit trails and data minimisation.

Help more viable businesses get a fair assessment.

We're looking for lending partners to pilot Cygnet Creations with a defined group of SMEs. Running a business? Join the waitlist and we'll let you know when you can take part.

We only use these details to reply to you.